Is Inflation the problem or is it really Consumerism
Inflation vs Consumerism: Are We Blaming the Wrong Thing for Our Financial Problems?
For years, we have been told that the rising cost of living is the reason we can't get ahead financially.
The mortgage is more expensive. Groceries cost more. Electricity bills have risen. Insurance premiums are higher. Petrol, rent, childcare and countless everyday expenses have all taken a bigger bite out of household budgets.
There is no question that inflation can make life more expensive.
But there is another conversation that is often missing: how much of our financial pressure is actually caused by inflation, and how much is caused by the way we have become accustomed to consuming?
It is an uncomfortable question because consumerism is remarkably good at disguising itself as necessity.
Inflation and consumerism are not the same thing
Inflation is an economic phenomenon. In simple terms, it means the general level of prices for goods and services rises over time, reducing the purchasing power of money.
Consumerism is different.
Consumerism is the culture and behaviour of continually buying goods and services, often beyond what we genuinely need. It is driven by convenience, advertising, social expectations, lifestyle aspirations, technology and the increasingly easy availability of things to buy.
One affects the price of what we buy.
The other affects how much we buy.
And the distinction matters.
If your weekly grocery bill has increased because food prices have risen, that is inflation.
If your grocery bill has increased because you now buy premium ready-made meals, multiple snacks, speciality coffees, delivery food and products you didn't previously purchase, that is not necessarily inflation.
It may be consumption.
Often, it is a combination of both.
The modern problem: our definition of "normal" has changed
Perhaps the biggest influence consumerism has had on personal finances is that it has gradually changed our expectations of what constitutes a normal lifestyle.
Think about some of the things that have become commonplace.
Multiple streaming subscriptions.
A new smartphone every few years.
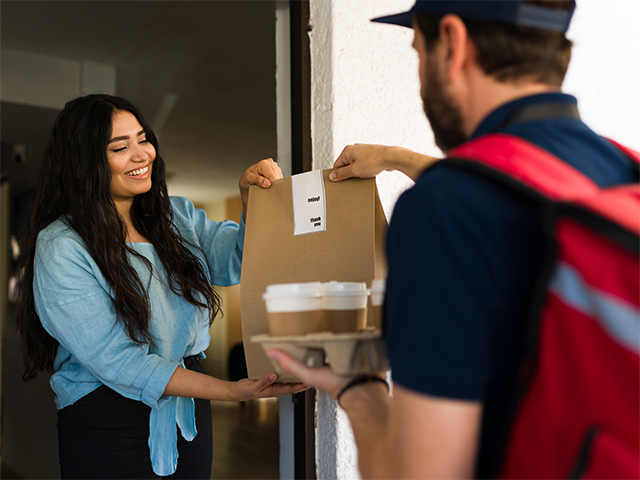
Food delivery several times a week.
Regular takeaway coffee.
Online shopping delivered to the front door.
Gym memberships and boutique fitness classes.
Frequent holidays.
New clothes because last season's clothes no longer feel current.
Homewares bought simply because they look good on social media.
Subscriptions that automatically renew.
Buy-now-pay-later purchases.
Upgrading perfectly functional cars, televisions, appliances and other technology.
Individually, many of these purchases don't seem particularly extravagant.
The problem is the cumulative effect.
A $7 coffee doesn't seem like a financial disaster. Neither does a $30 online purchase. Nor does another streaming service costing $15 a month.
But modern consumerism is built around small, frequent purchases.
And small purchases are surprisingly easy to ignore.
Lookback 20 years - lifestyle habits where to save over a 6 months, 1 year or even longer period - until you could afford that special item.
When "cost of living" becomes a catch-all explanation
The phrase "cost of living" has become almost synonymous with financial difficulty.
And there are certainly households where rising prices are genuinely making it difficult to cover essential expenses.
But there is a danger in treating every reduction in disposable income as an inflation problem.
Consider someone who says:
"I can't afford to save anymore because everything has become so expensive."
That statement might be completely accurate.
But it could also be worth asking a second question:
"What are you spending your money on today that you weren't spending it on five or ten years ago?"
That question can reveal something very different.
Perhaps the household is spending more on subscriptions, eating out, entertainment, online shopping, travel, technology and discretionary purchases than it once did.
The person's income may have increased.
Their essential expenses may have increased.
But their discretionary spending may have increased too " sometimes faster than their ability to save.
In that situation, inflation isn't necessarily the entire explanation.
We have become exceptionally good at justifying consumption
Modern marketing rarely tells us that we need to buy something.
Instead, it tells us that we deserve it.
You deserve the better version.
You deserve the upgrade.
You deserve to treat yourself.
You deserve the holiday.
You deserve the new wardrobe.
You deserve the latest phone.
You deserve the convenience.
This is powerful because consumption is no longer presented simply as spending money.
It is presented as self-care, success, convenience and even identity.
Social media adds another layer.
We are constantly exposed to other people's homes, holidays, cars, wardrobes, restaurants and lifestyles. What was once considered aspirational can quickly start to feel ordinary.
The result is lifestyle inflation: as income rises, spending expectations rise alongside it.
Instead of earning more and saving more, many people earn more and simply find more things to spend money on.
Bill insight - tally up the amount you are paying on freight because you can't be bother to walk to the shop.
The paradox of earning more but saving no more
This creates one of the strangest financial experiences of modern life.
Someone can earn substantially more than they did a decade ago and still feel financially worse off.
Some of that can absolutely be explained by higher housing and essential costs.
But lifestyle inflation can play a role too.
When income increases, the extra money often gets absorbed.
A slightly more expensive car.
A larger mortgage.
Better restaurants.
More frequent holidays.
More expensive clothes.
More subscriptions.
More entertainment.
More convenience.
Eventually, the higher income becomes the new normal.
And when prices subsequently rise, there is little financial buffer left.
The problem isn't necessarily that the person is earning too little.
It may be that their spending has expanded to consume almost everything they earn.
Consumerism makes saving feel like deprivation
Perhaps the most important psychological difference is how we perceive spending versus saving.
Spending produces an immediate reward.
Saving doesn't.
Buying something gives us something tangible today. Saving means deliberately choosing not to have something today in exchange for greater financial security tomorrow.
Consumer culture constantly reinforces the first behaviour.
Advertisers want us to buy.
Retailers make buying frictionless.
Payment technology makes spending almost invisible.
Online stores operate 24 hours a day.
Credit allows us to consume before we have actually earned the money.
Meanwhile, saving requires discipline and delayed gratification.
It is hardly surprising that the two behaviours don't always compete on equal terms.
Are we consuming more because things are cheaper?
There is another paradox.
Technology and mass production have made many consumer goods cheaper and more accessible than previous generations could have imagined.
Clothing, electronics, entertainment and household products can be purchased quickly and relatively cheaply.
But when something is inexpensive, we tend to buy more of it.
A $20 purchase doesn't receive the same psychological scrutiny as a $2,000 purchase.
Yet twenty $20 purchases are $400.
Consumerism doesn't necessarily require people to make one enormous financial mistake.
It can simply encourage thousands of small decisions that collectively consume their disposable income.
Inflation can be real and consumerism can be real too
This isn't an argument that people should stop talking about inflation.
Inflation matters.
When essential goods and services become more expensive, households genuinely lose purchasing power. For people on fixed or low incomes, the impact can be particularly significant because necessities make up a larger proportion of their budgets.
But acknowledging inflation doesn't mean ignoring personal consumption.
The two can exist simultaneously.
A household might pay more for groceries because of inflation while also spending more on takeaway food.
It might pay more for electricity while simultaneously running a larger home and more devices relient of electricity, phone,bikes, scooters,cars.
It might face higher mortgage repayments while also increasing discretionary spending.
It might complain about rising petrol prices while owning a larger, less fuel-efficient vehicle than it did previously.
None of these observations invalidate the reality of inflation.
They simply demonstrate that not every increase in household spending is inflation.
The uncomfortable savings question
Perhaps the more useful question isn't:
"Why can't I save as much as I used to?"
It is:
"Where is my money actually going?"
That means looking beyond the obvious bills.
Mortgage or rent.
Utilities.
Groceries.
Insurance.
Transport.
Healthcare.
Education.
Then look at everything else.
Subscriptions.
Restaurants.
Takeaway.
Coffee.
Clothing.
Online shopping.
Entertainment.
Holidays.
Hobbies.
Technology.
Home improvements.
Impulse purchases.
Convenience services.
Small recurring payments.
The answer can sometimes be surprising.
People often know exactly how much their mortgage costs each month.
Far fewer know how much they spend collectively on discretionary purchases.
The danger of blaming everything on inflation
There is a psychological benefit to blaming inflation for financial problems: it removes some of the responsibility from us.
If everything is expensive because of inflation, there is seemingly nothing an individual can do.
But if part of the problem is consumption, the situation is different.
Consumption can be examined.
Spending habits can be changed.
Subscriptions can be cancelled.
Impulse purchases can be reduced.
Lifestyle inflation can be reversed.
Savings can be prioritised.
None of these things will make groceries cheaper or mortgage rates lower.
But they can change the amount of money that remains after the essentials have been paid.
And that distinction is important.
The goal isn't to stop consuming
The answer isn't to live like a hermit, never eat at a restaurant or refuse to buy anything enjoyable.
Money is supposed to provide more than survival.
The issue is whether consumption is intentional or automatic.
There is a big difference between spending $200 on something you genuinely value and spending $200 because a targeted advertisement, social trend or momentary impulse convinced you that you needed it.
The first can be a conscious lifestyle choice.
The second can become a habit.
Financial health isn't necessarily about spending less on everything.
It is about spending less on the things that don't matter to you so that you have more money available for the things that do.
Inflation explains higher prices. It doesn't explain every spending habit.
The cost-of-living crisis has made household finances more difficult for many people.
But perhaps we also need to acknowledge a second crisis: the expectation that every increase in income should be accompanied by an increase in consumption.
For generations, financial progress was often associated with accumulating savings, reducing debt and building assets.
Today, progress can sometimes be measured by what we can afford to consume.
The bigger house.
The newer car.
The latest phone.
The overseas holiday.
The restaurant.
The designer purchase.
The endless stream of small conveniences.
And when the money disappears, inflation can become the easiest explanation.
The reality may be more complicated.
Sometimes the problem really is that things cost more.
Sometimes the problem is that we buy more things.
And increasingly, it may be both.
Perhaps the most useful financial question in today's consumer society isn't simply, "How much more expensive has life become?"
It's also:
"How much more have I come to expect from my money?"
That question can be uncomfortable.
But unlike inflation, it is one we can actually do something about.
Change your habits today, Save before you Shop, which will give more meaning to your purchases.
image credit istock Antonio_Diaz
MORE
GIRL.COM.AU
CONTACT US
FOLLOW US ON